My Family Used My Credit Card Because I Had “No Wife or Kids”—Then I Found Out What Else My Father Had Put in My Name
My Family Used My Credit Card Because I Had “No Wife or Kids”—Then I Found Out What Else My Father Had Put in My Name
My father laughed when I confronted him about the $2,342 charged to my credit card. “You don’t have a wife or kids, Nolan. Why shouldn’t you help the people who actually have families?” My sister told me to stop being dramatic, and my mother didn’t even look embarrassed. I didn’t yell. I went home, opened every financial account connected to my name, and started cutting them off. By morning, they were calling nonstop. Then someone sent me a photo of a foreclosure warning on my parents’ door—and I realized the stolen furniture was only the beginning.
Part 1
My name is Nolan Hayes, I’m thirty-two, and for most of my adult life, my family treated reliability like a tax I owed for making better decisions than they did. I work in IT in Denver, drive a six-year-old Honda, live below my means, and have never been especially interested in looking rich, but because I had savings and no children, every family emergency somehow became my problem. My younger sister, Bethany, had three kids and an impressive talent for turning temporary setbacks into permanent financial arrangements, while my brother Lucas moved from one business idea to another with the confidence of a man who had never personally absorbed the cost of failure. My parents, Diane and Robert, called me their “steady one,” which sounded affectionate until I realized it meant they expected me to stand still while everyone else leaned on me.
That Thanksgiving, I walked into my parents’ living room carrying a grocery-store pie and immediately smelled new leather, fresh carpet cleaner, and the faint chemical scent of electronics warming for the first time. Their old couch was gone, replaced by an enormous charcoal sectional, expensive curtains framed the windows, and a television nearly covered one wall; down the hallway, Bethany excitedly mentioned that her kids finally had the bunk bed they wanted. “Looks like somebody hit the lottery,” I joked, but Dad only lifted his beer and smiled. Mom changed the subject by asking whether I was “still wasting money on that expensive apartment,” and Bethany laughed, so I let the question go.
Three nights later, I was sitting at my kitchen counter with leftover Chinese food when I opened my credit-card app and saw a transaction for $2,342 from a furniture retailer I had never visited. The itemized receipt showed a sectional, television, curtains, bunk bed, delivery, and installation, and suddenly Thanksgiving replayed in my head with brutal clarity. I called the store, expecting fraud from a stranger, but the employee confirmed that an authorized user had made the purchase and that Robert Hayes had personally signed for delivery. Two years earlier, after Dad had surgery and my parents were struggling temporarily, I had added him to one card for groceries and medical expenses; I had forgotten to remove him, and apparently he had remembered perfectly.
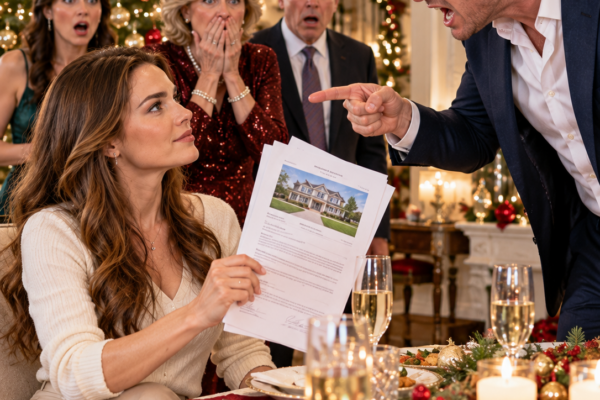
I drove to their house the next afternoon without warning, and Dad was sitting on my $2,342 sectional watching my $2,342 television when I asked, “Did you put all this on my card?” He laughed, actually laughed, and said, “You don’t have a wife or kids, Nolan. We figured you might as well help the people in this family who do,” while Mom folded laundry without looking up and Bethany rolled her eyes. “It’s not a big deal,” she said. “Stop being dramatic.” I looked at all three of them, smiled once, and said, “Then you’re going to love what happens next,” because at that moment I still thought I was dealing with one stolen purchase.
I was wrong.
Part 2
That evening, I muted the television, opened my laptop at the dining table, and started with the credit card because I wanted to know whether Dad had used it before. There were small charges I had overlooked for months—streaming subscriptions, auto parts, grocery deliveries, online purchases, household supplies—and each one was ordinary enough to disappear inside a statement unless someone deliberately searched for it. Then I noticed payments linked to accounts I barely remembered opening, including a $600 loan that carried my personal information even though I had no memory of requesting it. By midnight, cold coffee sat untouched beside my keyboard and the table was covered with yellow legal-pad pages filled with account numbers, dates, and questions.
The deeper I looked, the less accidental it seemed. There were documents connected to refinancing my parents’ vehicle, a family credit line that still had active charges, and old paperwork containing a version of my signature that looked familiar enough to make me uncomfortable but not familiar enough to reassure me. I remembered Dad sliding papers across the kitchen table during visits and saying, “Just sign here, son. It’s routine,” while somebody talked over the television and Mom asked me to fix her phone. I had trusted him enough not to read every page, and now that trust felt less like generosity and more like a door I had left unlocked.
I didn’t call anyone, because yelling would have given my family exactly what they understood: emotion they could argue with. Instead, I removed Dad as an authorized user, froze the questionable accounts, disputed the loan, added alerts to my credit profile, and reviewed every automatic payment I had ever agreed to cover. Electricity, water, gas, internet, insurance supplements—temporary help had quietly become permanent infrastructure, and some of those payments had continued for years without anyone asking whether I still consented. One by one, I stopped every payment that legally came from my accounts, documented what I had done, closed my laptop around 1:30 a.m., and slept better than I expected.
My phone began vibrating before seven the next morning. Bethany called, Mom called, Dad called, the house phone called, and soon messages started appearing: “Something is wrong with the utilities,” “Did you change the card?” “The bank called about the loan,” and finally Dad wrote, “You’re crossing a line. Stop acting like a child and take responsibility for your family.” By noon, I had seventy-four missed calls, but the message that finally made my stomach tighten came from an unknown number and contained only a photograph of my parents’ front door. An official envelope had been taped beside the handle, and across it were the words “FINAL NOTICE BEFORE FORECLOSURE.”
I stared at the picture for a long time, because shutting off my money shouldn’t have brought their entire financial life to the edge of collapse overnight.
Unless I had been holding up far more than I knew.
Part 3
By the following afternoon, relatives I normally heard from twice a year had suddenly developed passionate opinions about my responsibilities as a son. Aunt Marilyn called it a “family misunderstanding,” my cousin Jenna said my parents were getting older and needed compassion, and another relative gently suggested that Bethany’s children should not suffer because the adults were fighting. Their wording was so similar I could practically hear my mother rehearsing it before handing them the phone. Nobody asked why my credit card had been used without permission; they asked when I was going to start paying again.
I stopped explaining myself and hired an attorney named Daniel Mercer, a calm man in his fifties whose office smelled like printer toner and burnt coffee. I brought him a folder thick enough to need both hands, and for nearly two hours he asked questions while I described the card, the loan, the vehicle refinancing, the automatic bills, and years of documents I had signed without understanding how they connected. “From now on,” he said, tapping the folder, “facts, records, and no private agreements with your family.” We froze access where appropriate, notified the credit bureaus, requested documentation from lenders, and began separating what I had knowingly authorized from what I had not.
Bethany showed up at my apartment four days later. Through the peephole, I saw mascara streaked beneath her eyes and a stack of papers pressed against her chest, and when I refused to open the door she started pounding hard enough to make my neighbor step into the hallway. “Nolan, fix this!” she shouted before sliding a furniture bill beneath my door, and across the top she had written those same two words in red marker: FIX THIS. I photographed everything, sent it to Daniel, contacted the retailer through the formal dispute process, and never answered Bethany directly.
Dad’s email arrived that night with no subject line and one sentence: “You’ve made enemies out of your own blood. Good luck sleeping at night.” I read it twice, then closed my laptop and slept for almost nine hours, which probably would have infuriated him more than any reply. For the next three days my phone stayed quiet, and I used the silence to change passwords, close old accounts, tighten security, and finally change the phone number I had kept since college. I thought perhaps the worst part was over.
Then my company’s HR department asked me to come upstairs.
Someone had anonymously accused me of financial misconduct involving company money.
Part 4
Our HR director, Melissa, did not treat me like a criminal, which was the first reason I managed to keep my voice steady. She explained that the report contained claims about company funds and outside accounts, but several details were obviously inconsistent with their internal records; they still had to document the complaint because that was policy. I told her I was involved in a family financial dispute, showed her the attorney’s contact information, and gave only the facts necessary to protect myself. I couldn’t prove my parents or Bethany had made the accusation, so I didn’t accuse them, but Daniel added the incident to our growing file and sent formal instructions demanding that my family stop contacting me through third parties.
While reviewing old digital records, I discovered a shared document platform my parents had used years earlier when refinancing their home. I had forgotten the login still existed, but once I opened it, folders appeared containing tax documents, bank statements, incomplete loan applications, utility records, credit authorizations, and copies of my personal financial information. Some documents included my banking details even though I wasn’t listed as the primary borrower, and other pages contained signatures that made my skin prickle because they looked like somebody had practiced writing my name. I stopped opening files after that, preserved everything exactly as I found it, and sent the material to Daniel.
A mortgage-lender representative named Thomas Reed called the following week. He was careful with his wording, but he wanted to understand why my banking information appeared inside parts of my parents’ refinancing history when I was not currently listed on their mortgage. I answered only what I knew, gave him permission to coordinate through my attorney where necessary, and provided the preserved records instead of trying to interpret them myself. By Friday, the lender had expanded its review, and suddenly the $2,342 furniture purchase looked less like the problem and more like the loose thread that had opened an entire seam.
That night, a photograph arrived on my new number from an unknown sender. A small wooden box sat on my parents’ porch, and the name MAX had been painted across the lid; Max had been my childhood dog, the one creature in that house who never measured my value by what I could fix or pay for, and he had died two years earlier. Beneath the box, someone had placed cardboard with a handwritten question: “IS THIS WHAT YOU WANTED?” I felt something inside me finally turn cold.
They were willing to use money, relatives, my job, and even the memory of my dog to drag me back into place.
I forwarded the photograph to Daniel and understood that reconciliation was no longer something I wanted.
Part 5
Two weeks later, Daniel called shortly before lunch and asked whether I was somewhere private. The lender’s review had identified serious irregularities in the refinancing records: inconsistent authorizations, financial information that did not match supporting documents, disputed signatures, and paperwork tied directly to Dad’s involvement. Daniel was careful not to turn preliminary findings into accusations, but the lender no longer considered the situation a harmless clerical mistake, and the existing mortgage problems had become harder for my parents to hide. The house was already behind on payments, and without outside money keeping other bills afloat, there was nothing left to absorb the damage.
For years, my family had described every request as an isolated emergency. Dad needed help after surgery, Bethany needed groceries, Lucas needed money to launch another company, Mom worried about utilities, someone needed Christmas gifts, somebody’s car broke down, somebody forgot insurance, somebody was short on rent. Looking at the records now, I understood the trick: there had never been one emergency at a time. They had built a lifestyle around the expectation that whenever the numbers stopped working, Nolan would make them work again.
Mom’s handwritten letter arrived three days later in the same blue ink she had used on every birthday card when I was growing up. She moved from sadness to blame across four pages, accusing me of humiliating them, upsetting Bethany’s children, turning relatives against the family, and destroying the home Dad had worked “his entire life” to preserve. Then I reached the sentence I read three times: “After everything we’ve done for you—raising you, feeding you, giving you a roof over your head—you repay us by acting like a stranger. You’re lucky we allowed you to belong to this family at all.” I sat at my kitchen table with the afternoon sun hitting the paper and finally understood why helping had never made me feel loved.
My place in the family had always come with an invoice. I was useful when I paid, dependable when I solved things, generous when I ignored my boundaries, and selfish the moment I asked them to stand on their own. I folded Mom’s letter, placed it in the legal file instead of answering it, and finished a formal statement explaining exactly what financial access I had knowingly granted and what I disputed. A few days later, an online property notice appeared with an address I knew by heart.
My parents’ house had entered foreclosure proceedings.
And for the first time, I didn’t reach for my checkbook.
Part 6
Bethany posted about me on Facebook almost immediately, although she was careful not to mention the credit card, the loan, or the disputed financial documents. According to her version, an unnamed relative with “more money than compassion” had chosen to watch aging parents lose their home over “one small mistake,” and several cousins initially filled the comments with sympathy. Then Uncle Grant asked why using someone else’s credit was being described as a mistake, and another cousin asked why I had apparently been responsible for my parents’ utilities in the first place. Bethany deleted the post within an hour, but I saved screenshots and went back to work.
Dad’s final voicemail arrived several weeks later. His voice had lost the confident edge I remembered from the day he stood beside the new television and told me my money belonged to people with “real families,” and there were long pauses between his sentences. “The house is gone,” he said. “Your mother and Bethany are staying with Marilyn. Bethany barely speaks to me. I know you’re angry, Nolan, and I made mistakes… we all did. If there’s any part of you that still cares, please call.”
I sat on the edge of my bed listening to the refrigerator hum in the next room, waiting for the guilt to arrive. It didn’t. I didn’t hate Dad, and that surprised me, but hatred would have required a kind of emotional attachment I no longer had; what I felt was distance, almost like looking at a house I had moved out of years ago and realizing somebody else’s lights were on inside. I deleted nothing, saved the voicemail with the rest of the records, and never called him back.
A month later, the property appeared as bank-owned, and one Saturday afternoon I drove past the house because I wanted to see whether losing it would finally make everything feel real. The grass had grown high along the walkway, the mailbox bulged with old envelopes, the curtains were gone, and through the front window I could see pale rectangles where pictures had once hung; that enormous television was gone too. I remembered Thanksgiving, Dad raising his beer, Bethany admiring the furniture, and Mom criticizing my apartment while they sat in a room partly paid for with money they had taken from me. The house looked strangely small.
That evening, I opened an old folder on my laptop labeled “Denver Plans.”
Inside were homes I had spent years telling myself I would buy someday.
This time, nobody else’s emergency was going to come first.
Part 7
For years, every time my savings reached a number that made homeownership realistic, something happened. Bethany needed a deposit, Dad had a payment due, Lucas discovered another “once-in-a-lifetime” investment, Mom called about an overdue bill, and I postponed myself because saying no felt crueler than losing another year. Without those withdrawals, my finances changed faster than I expected. Three months after opening that folder, I signed papers on a two-bedroom condo in a quiet brick building west of downtown Denver, with polished wood floors, tall windows, and a view that turned gold in the late afternoon.
The first night, I ate pizza sitting on the floor because my dining table had not arrived yet. The rooms smelled like fresh paint and cardboard, traffic whispered far below the windows, and every unopened box belonged to me because I had chosen it, not because somebody had used my name to order it. I bought furniture slowly, picked artwork nobody else approved, and turned the second bedroom into an office without hearing Bethany complain that one of her kids “needed the space more.” The ordinary freedom of deciding what happened inside my own home felt more luxurious than anything I had ever purchased.
I began spending holidays differently too. Sometimes friends came over, sometimes I visited people who had shown up for me without expecting money, and one Thanksgiving I cooked a steak, opened a good bottle of wine, and watched snow fall over Denver by myself. Nobody called me selfish for buying something nice, nobody shoved a bill across the table, and nobody reminded me that because I wasn’t married or raising children, my life somehow mattered less. Silence, I discovered, was not loneliness when it belonged to you.
I never reconciled with my parents, Bethany, or Lucas. A few relatives eventually reached out after learning more about what had happened, and I stayed civil with the ones who could speak to me without asking when I planned to forgive everyone, but I stopped believing forgiveness was a debt owed on demand. Maybe my parents regretted losing the house, maybe Dad regretted the paperwork, and maybe Bethany regretted the day she told me $2,342 wasn’t a big deal; none of those regrets changed what they believed until consequences made that belief expensive. Their love had arrived wrapped around entitlement for too many years, and I had no interest in returning to the arrangement simply because they finally disliked the price.
Looking back, the turning point wasn’t the foreclosure, the lender’s investigation, or even the questionable documents. It was Dad standing in that newly furnished living room, beer in his hand, smiling as he told me that because I had no wife or children, my future was somehow less important than everyone else’s comfort. For most of my life, I had confused being needed with being loved, and every rescue had taught them that my boundaries could be ignored if the emergency sounded urgent enough. The night I found that charge, I finally stopped teaching them that lesson.
I didn’t destroy my family by refusing to pay.
I simply stopped financing a relationship that required me to disappear inside it.
Now, when I lock my own front door at night, every bill behind that door is mine because I chose it, every person who enters is there because I invited them, and nobody else has a key to my peace.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓