My Father Screamed, “You’re No Daughter of Mine!”—Two Weeks Later, He Was Still Trying to Spend My Money, Until I Revealed What I’d Discovered
My Father Screamed, “You’re No Daughter of Mine!”—Two Weeks Later, He Was Still Trying to Spend My Money, Until I Revealed What I’d Discovered
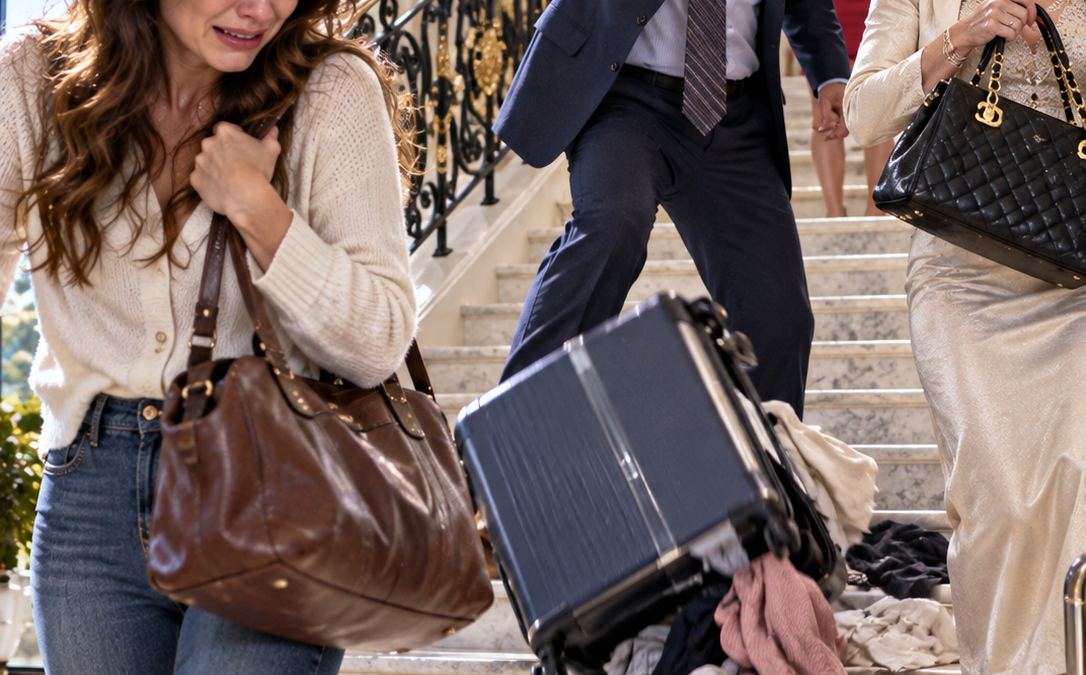
“GET OUT! YOU’RE NO DAUGHTER OF MINE!” my father screamed, throwing my suitcase down the marble staircase. My mother stood beside him, smiling with a $12,000 designer handbag I’d unknowingly paid for. My younger sister had only one concern: “Before you leave, give us your credit card.” For 7 years, I’d financed their luxurious lives, but the moment I questioned a suspicious $48,000 purchase, they disowned me. I walked away quietly. Two weeks later, they were still trying to spend my money, completely unaware of what my attorney had uncovered.
Part 1/5
The sound of my suitcase hitting the marble staircase was louder than my father’s voice, which was impressive because he’d been shouting for nearly 10 minutes. It bounced down six steps, struck the wrought-iron railing, and burst open, scattering my clothes across the polished floor. My mother stood beside him holding a cream-colored designer handbag, her expression suggesting she’d been waiting years for this particular performance. “Get out, Claire!” Dad roared. “You’re no daughter of mine!”
My name is Claire Halden, I’m 34 years old, and until that Friday evening, I’d been financing my family’s lifestyle for almost 7 years. My father, Martin, owned a construction company outside Charlotte, North Carolina, while my mother, Patricia, considered shopping an essential occupation. My younger sister, Brielle, was 29 and hadn’t held a full-time job since graduating from college. Somehow, I was the selfish one whenever I suggested they spend less.
I hadn’t arrived expecting an argument. I’d driven over after receiving a troubling notification about a $48,000 jewelry transaction linked to an authorized family spending card on my account. The bank had flagged the transaction before processing it, and I’d called Mom to ask what was happening. She’d explained that Brielle was getting engaged and deserved a spectacular diamond necklace to celebrate.
“Forty-eight thousand dollars?” I’d repeated, certain there had been a misunderstanding. Mom had responded that I couldn’t possibly understand how expensive maintaining a respectable social position had become. When I suggested Brielle’s boyfriend might purchase her engagement jewelry himself, Mom accused me of being jealous. That was usually how our financial conversations ended: someone insulted me, and I paid anyway.
This time, I hadn’t paid. Instead, I’d requested a complete statement of the family card, which was an additional card on an account I owned. I discovered resort charges, luxury clothing purchases, restaurant bills, and a $12,000 handbag purchased without my knowledge. The handbag was now hanging from my mother’s arm as she watched Dad throw me out.
Dad had his own demands. His construction business, Halden Builders, supposedly needed another $200,000 to cover a temporary shortage in its operating account. I’d asked to review the company’s financial statements before providing additional money, which made him furious. He accused me of forgetting who’d raised me, despite the fact that I’d supported myself since college.
“You think your fancy investment business makes you better than us?” he demanded. I told him that earning money didn’t make me superior, but it gave me the right to decide how that money was spent. His face darkened, and he pointed toward the front door. “Then take your money and get out of my house.”
I bent to collect my scattered clothes, ignoring the sharp sting behind my eyes. I’d helped maintain that house, paid several overdue property expenses, and covered the down payment on my mother’s luxury SUV. But the property belonged to my parents, and I had no desire to stay where I wasn’t welcome. I packed my belongings while Dad continued describing me as ungrateful.
Brielle appeared halfway down the staircase wearing silk pajamas and expensive slippers. She watched me close my suitcase, then extended her hand. “Before you leave, give us your credit card,” she said casually. “Mom and I have a shopping appointment tomorrow, and we already reserved some things.”
For a moment, I thought she was joking. “Dad just said I’m not part of this family anymore,” I reminded her. Brielle shrugged and replied that personal arguments shouldn’t interfere with financial responsibilities. My mother nodded as though her explanation made perfect sense.
Dad folded his arms. “After everything we’ve done for you, paying a few bills is the least you owe us.” I looked at the three people standing beneath the enormous chandelier and finally recognized something I’d been refusing to admit. They weren’t frightened of losing their daughter or sister. They were frightened of losing access to her bank account.
I picked up my suitcase and walked toward the door. Brielle called after me, “Good luck finding anyone who actually loves you when you stop buying things for them.” I turned around and said, “You might want to check your accounts tomorrow.” Then I stepped outside into the chilly evening and closed the door behind me.
Inside my car, my hands trembled so badly that I couldn’t immediately start the engine. I called my attorney, Leah Rowan, who’d been quietly reviewing certain business records for the previous month. “Are you ready?” she asked after hearing my voice. I looked back at the illuminated windows and told her to cancel the spending card, revoke every financial authorization, and send the notices we’d prepared.
Leah was silent for a moment. “Claire, once those notices go out, your father will know you’ve started asking the right questions.” I glanced at the folder sitting on my passenger seat, containing records that didn’t match the explanations Dad had given me. “Good,” I answered. “Because I think he’s been using more than my credit card without permission.”
Part 2/5
The first furious call arrived at 10:14 the following morning, just as I was making coffee in my apartment. Brielle had apparently attempted to purchase a $6,800 handbag at an upscale department store, only to discover that her card no longer worked. She didn’t bother asking whether something had happened to my account. “Claire, fix your stupid card,” she demanded. “I’m standing here looking like an idiot.”
“That’s because I canceled it,” I explained, pouring coffee into my favorite chipped mug. She laughed, assuming I was joking, and told me to reactivate it immediately. When I refused, she shouted for our mother, who took the phone and accused me of deliberately humiliating my sister. I ended the conversation after reminding them that they were welcome to purchase anything they could afford themselves.
Over the next several days, the calls multiplied. Mom wanted a $14,200 resort reservation restored, while Brielle complained about a declined furniture purchase. Dad demanded that I resume making payments on his vehicle and stop interfering with expenses he’d supposedly approved months earlier. Every conversation ended with someone threatening to cut me off from a family that had already disowned me.
I blocked the spending card permanently and arranged for the issuer to reject any remaining merchant authorizations. Separately, I reviewed every automatic payment I’d been covering voluntarily and notified the relevant businesses where responsibility would need to return to my parents. I wasn’t canceling contracts belonging to other people; I was stopping my money from being used to fund them. For the first time in years, I could open my banking app without wondering what surprise awaited me.
But the family spending account wasn’t what concerned Leah. Seven years earlier, I’d rescued Halden Builders through a $750,000 secured commercial loan issued by my investment company, Northlake Capital. The agreement allowed Dad to retain management control while requiring scheduled payments and financial reporting. For several years, he’d complied, but the payments had recently stopped.
When I’d requested updated records, Dad repeatedly blamed his accountant. He insisted the company was profitable and that delays were caused by customers who hadn’t paid their invoices. Something about his explanation bothered me, particularly because several large payments had left the company’s accounts during the same period. I asked Leah to arrange an independent forensic review rather than rely on documents supplied directly by my father.
On Monday afternoon, Leah arrived at my office carrying two thick folders. She placed the first on my desk and explained that investigators had identified questionable payments to three entities. One was associated with Brielle, another had paid for personal expenses benefiting Mom, and the third was a consulting business called Crestview Advisory. Its registered owner was Dad’s longtime business partner, Russell Pike.
“How much money are we talking about?” I asked. Leah opened the second folder and showed me a schedule of invoices totaling nearly $620,000. Several described consulting work connected to construction projects that our investigators couldn’t verify. Each carried an electronic approval attributed to me, even though I hadn’t been involved in the company’s purchasing operations for years. I stared at the familiar digital signature appearing beneath transactions I had never seen.
“I didn’t approve these,” I said. Leah nodded and showed me the authentication records obtained from systems to which our loan agreement gave us audit access. The approvals appeared to have been submitted using old credentials associated with my former advisory role, with access originating from equipment in Dad’s office. The evidence didn’t yet establish who had used the credentials, but it was serious enough for us to preserve everything and notify the appropriate investigators.
Then Leah showed me another document. Dad had applied for a $1.4 million refinancing package, representing that the business had stronger financial reserves than our review suggested. His application also appeared to omit material details concerning Northlake Capital’s existing secured claim. The lender had requested additional documentation, and Dad needed our cooperation to move forward.
Suddenly, his demand for $200,000 made more sense. He wasn’t merely asking for help with operating expenses; he might have been trying to conceal a larger financial problem until the refinancing closed. I remembered how quickly he’d thrown me out when I requested the books. His anger had protected him from answering questions he couldn’t afford to answer honestly.
Two weeks after the confrontation, Brielle posted photographs from a luxury car showroom. Minutes later, Dad called demanding that I authorize an $86,500 vehicle purchase she’d apparently arranged using my canceled account. I refused, and he threatened to make certain no relative ever spoke to me again. “Dad,” I said quietly, “the credit card is the smallest problem you have.”
He accused me of blackmail and hung up. An hour later, Leah confirmed that the refinancing lender had received the relevant notices and suspended its review pending further verification. Then she forwarded a message from my aunt saying Dad had summoned twelve relatives to an emergency family meeting. According to him, I was attempting to steal Halden Builders out from under its rightful owner.
I read the message twice, feeling a strange calm settle over me. Dad had spent years using family gatherings to pressure me into surrendering whenever I questioned him. This time, however, he was inviting witnesses to a conversation he’d worked desperately to avoid. I called Leah and said, “Tell him I’ll be there, but you’re coming with me.”
Part 3/5
The following evening, I pulled into my parents’ circular driveway at 6:55. Every downstairs window glowed, and the landscaping lights illuminated the expensive stonework I’d helped pay to repair 3 years earlier. Leah sat beside me holding the forensic accountant’s preliminary report, while our accountant, Simon Price, followed in his own car. Before we got out, she reminded me to remain calm and avoid making accusations that the evidence couldn’t yet support.
Twelve relatives were waiting inside the formal dining room. Dad occupied his usual chair at the head of the table, Mom sat beside him clutching another designer handbag, and Brielle was wearing diamond earrings I’d never seen before. Russell Pike stood near the fireplace, nervously turning his wedding ring. Nobody greeted me when I entered, although several relatives watched Leah with obvious curiosity.
“Well, the prodigal daughter finally returns,” Dad announced. He pointed toward an empty chair but made no effort to introduce my guests. Mom immediately demanded an apology for the embarrassment I’d caused Brielle at the department store. My sister added that I needed to reactivate the spending card before her engagement celebration.
I sat down and placed my purse beside the chair. “That card belonged to my account, and it’s permanently canceled,” I explained. Dad slammed his palm against the table hard enough to rattle the silverware. “You don’t get to punish this family because your feelings are hurt!”
“I’m not punishing anyone,” I replied. “I’m refusing to keep financing people who told me I wasn’t family.” My aunt, Denise, looked between us and asked why a 34-year-old woman was expected to cover everyone else’s shopping expenses. Mom immediately changed the subject, claiming she’d sacrificed everything raising me. I noticed that nobody answered Denise’s question.
Dad then announced that I was trying to take his construction company. He told our relatives I’d become obsessed with controlling the family business and was using my wealth to force him into surrendering it. I opened my folder and placed the signed loan agreement on the table. “Seven years ago, Northlake Capital loaned Halden Builders $750,000,” I explained. “Dad signed a commercial agreement, not a family gift receipt.”
Leah distributed copies of the relevant documents while Simon prepared the supporting financial schedules. The company had missed required payments, and our agreement provided specific remedies for default. Dad insisted he’d made every payment, but Simon displayed the bank reconciliation showing otherwise. When my uncle asked why Dad hadn’t mentioned the loan, my father’s expression became noticeably strained.
“That’s not even the worst problem,” I continued, turning to the next section. I showed them the questionable invoices, carefully explaining that the investigation remained ongoing. Several appeared to describe nonexistent services, and electronic approvals had been submitted through credentials associated with my former role. “I never approved these transactions,” I said, watching Dad’s reaction.
Russell stopped turning his ring. He glanced toward the hallway, but Leah asked him whether he recognized Crestview Advisory, the business named on several invoices. He answered that it provided legitimate consulting services and insisted there was nothing suspicious about receiving payment. Simon quietly asked him to identify the construction projects on which those services had supposedly been performed.
Russell couldn’t name one.
Brielle interrupted, accusing us of manufacturing accusations to embarrass her. I turned to a financial schedule showing more than $62,000 transferred to an account associated with her supposed consulting work. “What services did you provide?” I asked. She stared at the page, then claimed Dad had told her it was compensation for helping with company marketing.
“Then there should be records of that work,” Leah explained. Brielle looked at Dad, waiting for him to rescue her, but he was busy accusing Simon of misinterpreting ordinary business expenses. Russell suddenly stepped forward and blurted, “Martin, I told you using Claire’s approval credentials was a terrible idea!” The room fell silent.
Dad spun toward him. “Shut your mouth, Russell!” My aunt pushed her chair back and asked whether they’d deliberately used my identity to approve company payments. Russell stared at the floor, realizing what he’d said in front of twelve witnesses. I felt sick, but also strangely relieved, because someone had finally admitted the possibility I’d been investigating for weeks.
Leah placed a formal default notice and proposed repayment framework before Dad. The refinancing lender had suspended its review, and Northlake would pursue the contractual protections available under the loan agreement. Dad stared at the documents, then looked at me with an expression that shifted from fury to disbelief. “You’re really willing to destroy your own father over money?”
I held his gaze. “You disowned me because I asked where my money was going,” I answered. “You still expected me to pay for your vacations, jewelry, and cars, and now I’m discovering that someone may have used my identity to approve false transactions.” He opened his mouth, but I continued before he could interrupt.
“You told me I wasn’t your daughter. From now on, you’ll deal with me as a creditor.”
Nobody spoke until my mother whispered, “What happens to the house?”
Leah answered calmly that the house wasn’t collateral for Northlake’s loan, although the family’s wider financial problems would need to be addressed separately. Dad stared at the documents, unable to command the room back into submission. Then Russell quietly asked a question that revealed just how frightened they really were.
“Martin, did you tell her about the second set of invoices?”
Part 4/5
Dad’s head turned so sharply that his chair scraped against the floor. “There is no second set,” he snapped, but Russell was already reaching for his phone. He explained that additional invoices had been submitted through a different accounting platform, supposedly to cover specialized project-management services. Leah asked him to preserve whatever records he possessed and provide them through counsel. For the first time, I saw my father genuinely afraid of someone other than me.
I didn’t stay to watch the argument. Leah advised against turning the meeting into an uncontrolled confrontation, and I agreed because we’d already accomplished what mattered. Several relatives approached me near the front door, asking questions and expressing shock that Dad had borrowed such a large sum without mentioning it. My aunt Denise quietly apologized for believing his stories about my supposed greed.
“Why didn’t you tell us sooner?” she asked. I considered explaining how often I’d been punished for disagreeing with Dad, but I was exhausted. “Because every time I talked about money, someone told me I was destroying the family,” I answered. Denise looked back toward the dining room, where raised voices had begun echoing through the hallway.
The next morning, Leah received a call from Russell’s attorney. His client was willing to cooperate with investigators and provide access to records concerning the additional invoices. Those materials suggested that fictitious consulting charges had been used to disguise transfers among several businesses. Some records also showed that money had been diverted to cover personal expenses during periods when legitimate contractors were waiting for payment.
The new information didn’t mean every questionable transaction was criminal. Simon carefully separated expenses supported by legitimate documentation from payments requiring further investigation. But the pattern was serious enough for outside investigators to continue reviewing access logs, vendor records, and financial statements. Meanwhile, Halden Builders faced immediate difficulties because its refinancing had stalled and the outstanding loan remained in default.
Dad tried calling me repeatedly. At first, his messages were threatening, promising lawsuits and telling me I’d regret attacking him. Then he switched tactics, claiming his health was suffering and that Mom couldn’t sleep because of what I’d done. When I didn’t respond, he sent a photograph of the house with the caption, “This is where your family raised you. Don’t let strangers take it away.”
I forwarded the message to Leah and returned to work.
Four months later, Halden Builders entered a court-supervised restructuring process. The company sold nonessential equipment, surplus vehicles, and certain business assets to reduce its debts while continuing a smaller portion of its operations. Northlake recovered a substantial amount of its outstanding loan, with the remaining balance governed by a repayment arrangement. I didn’t receive a windfall; I recovered money that had been contractually owed to my business.
The criminal investigation continued independently of those financial proceedings. Russell faced charges related to fraudulent invoices and agreed to cooperate with prosecutors. Dad was eventually charged over unauthorized electronic approvals and false financial representations, and he later entered a guilty plea under an agreement that included restitution and court supervision. I attended the relevant proceedings because my identity had been used without permission, not because I enjoyed seeing him humiliated.
Brielle reached a civil repayment agreement concerning money she’d received through the consulting arrangement. Without access to my spending card, she had to find employment and sell several luxury purchases. Mom and Dad sold their expensive vehicles and eventually moved into a smaller rental after choosing to sell the family house. Their lifestyle changed dramatically, but none of that required me to celebrate their suffering.
What hurt most was realizing how quickly their affection changed once they understood I wouldn’t surrender. Mom called to describe herself as heartbroken, then casually asked whether I could cover Brielle’s rent until she found steadier work. Brielle sent a message saying I should help because she was still my sister. Neither asked what it had felt like to watch my clothes scattered across the marble staircase.
I declined every request and stopped answering financial questions.
Six months after the family meeting, Dad sent a handwritten letter to my office. It was the first personal correspondence I’d received from him that didn’t contain an immediate demand. He admitted he’d confused providing for his family with controlling them and wrote that he’d forgotten loving me was supposed to matter more than what I earned. For several minutes, I sat holding the letter while old memories crowded into my mind.
I remembered him teaching me to ride a bicycle, cheering at my college graduation, and telling me that hard work would make me independent. Those memories had once persuaded me to excuse almost anything he did. But I also remembered his face when he threw my suitcase down the stairs, and how completely he’d withdrawn his love when I refused him money. A letter couldn’t undo that history.
I placed it in a drawer without replying.
A week later, my attorney called with an update about the remaining financial proceedings. Then she mentioned that Dad had contacted her office with another proposal, one that made it clear he still hadn’t fully accepted my decision.
He wanted me to forgive the outstanding balance as a condition of “restoring our family.”
Part 5/5
I almost laughed when Leah told me about Dad’s proposal. He wanted Northlake Capital to forgive the remaining debt, withdraw its civil claims, and provide a letter confirming that our financial disputes had been resolved. In exchange, he promised to welcome me back into the family and stop telling relatives I’d betrayed him. Apparently, he still believed having access to my parents was a privilege I should purchase.
“Tell him the repayment agreement remains in effect,” I said. Leah asked whether I wanted to include a personal message, but I shook my head. I’d spent 7 years explaining my feelings to people who listened only when money was involved. Another explanation wouldn’t change anything.
The following months were quieter than I expected. Without my family’s constant requests, I had time to focus on Northlake Capital and the clients who’d actually trusted me with their financial futures. I expanded our small investment team and established a scholarship program for young women pursuing finance degrees. I wanted those students to understand something I’d learned painfully: financial independence meant very little unless you also knew how to protect it.
My closest friend, Hannah, noticed the change before I did. We’d been friends since college, but for years I’d canceled dinners whenever Mom needed shopping money or Dad demanded help with an unexpected business problem. One Friday, Hannah invited me to spend the weekend at her family’s lake house. I accepted without checking whether anyone in my family might need me.
We spent Saturday morning drinking coffee on the dock while sunlight scattered across the water. Hannah asked whether I missed my parents, and I admitted that sometimes I did. I missed the family I’d wanted us to become, the imaginary version where my father was proud of me without demanding repayment and my mother loved me without comparing me to Brielle. But I didn’t miss being responsible for everyone’s happiness.
A year after Dad threw me out, I purchased a modest lakefront home about an hour outside Charlotte. It had a wide wooden porch, three bedrooms, and enormous windows overlooking the water. I furnished it gradually, choosing comfortable chairs instead of expensive decorations meant to impress visitors. For the first time, every decision about my home belonged to me.
On moving day, Hannah arrived carrying pizza and a bottle of sparkling cider. We sat on the unfinished living-room floor surrounded by cardboard boxes, laughing when we discovered I’d forgotten to bring silverware. I remembered the enormous chandelier hanging above my parents’ marble staircase and realized I’d never felt as comfortable in their house as I did sitting on my own floor eating pizza from a paper plate.
That evening, Brielle sent me a message.
“Do you think we’ll ever be a family again?”
I stared at the screen, considering the question. Part of me wanted to explain that we’d never really been the family she imagined, because love shouldn’t disappear when someone refuses to pay for a necklace. Another part wanted to ask whether she’d finally found work she enjoyed, whether she understood what happened, or whether she was simply hoping the money would return.
Instead, I replied, “I hope you’re building a good life, Brielle. But I won’t return to the relationship we had, and I won’t support you financially again.”
She responded with a single sentence: “You’re still holding a grudge.”
I put the phone down without answering.
A few weeks later, Dad’s letter appeared again while I was organizing old documents. I read his words more carefully this time and wondered whether he genuinely regretted his behavior. Perhaps he did, but remorse arriving after financial consequences wasn’t enough to erase years of entitlement. He’d had countless opportunities to treat me like a daughter before the bank accounts stopped working.
I kept the letter in a box of family photographs, but I didn’t contact him.
That Christmas, I invited Hannah and several friends to my lake house. We cooked together, exchanged inexpensive gifts, and spent the evening playing board games beside the fireplace. Nobody asked what their presents cost, nobody demanded my credit card, and nobody expected me to prove my love by paying their bills. When I looked around the table, I realized I’d found the kind of family atmosphere I’d been trying to purchase for years.
Later, after everyone left, I stepped onto the porch carrying a blanket and a mug of hot chocolate. The lake was perfectly still beneath the moonlight, and the only sound came from wind moving through the pine trees. I thought about the night Dad threw me out, and how terrified I’d been that losing my family meant losing everything. I could see now how wrong that fear had been.
My parents were responsible for their choices, and Brielle was responsible for hers. Whether they changed someday was no longer something I needed to control, finance, or wait around to witness. I had my business, my friends, my home, and the freedom to spend my money without asking anyone’s permission. More importantly, I finally understood that being loved shouldn’t require making myself useful.
I took one final sip of chocolate and watched the moon’s reflection ripple across the lake.
My father had screamed that I wasn’t his daughter because I refused to give him another $200,000. For weeks afterward, my family had continued trying to use my canceled card, convinced I’d eventually surrender and restore their luxurious lives. Instead, I’d uncovered the truth, protected what I’d built, and walked away from a relationship that had become little more than an expensive obligation.
They thought throwing me out would frighten me into paying.
What they never understood was that the moment I left their house, I stopped paying people to pretend they loved me.
And I never went back.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓