Driving home after six months away, I expected the worst thing waiting for me would be an empty………
Driving home after six months away, I expected the worst thing waiting for me would be an empty refrigerator and a house that smelled closed up. Instead, someone had pasted a fluorescent foreclosure notice across my front door. Forty-seven days until auction. The house was paid off. At least, I had believed it was.
Part 1: A Foreclosure Notice Exposes an Impossible Debt on My Home
By the time I reached my townhouse outside Columbus, I had been awake nearly twenty-four hours. My mother’s stroke had pulled me three states away in April, and a two-week emergency had become six months of rehab appointments, insurance calls, and sleeping from a suitcase. I wanted my own bed and a few hours without anyone asking me to make a decision.
The orange notice on my front door took care of that fantasy.
PINNACLE UNION BANK — NOTICE OF FORECLOSURE.
I read it twice. Public auction in forty-seven days. I stared at the brass numbers above the door as if I might have driven to the wrong address.
I had paid off the townhouse two years earlier. I remembered sending my younger sister, Melissa, a photograph of the “PAID IN FULL” letter. She had replied, “Dad would be proud.”
Inside, I left my bags in the entryway and opened my laptop at the kitchen island. I work in bank risk management, so mortgages, title defects, and compliance failures are familiar territory. On the county recorder’s site, my original mortgage release sat exactly where it belonged.
Then I saw the next entry.
A deed of trust recorded eight months earlier.
Principal: $800,000.
Borrower: me.
The signature at the bottom was close enough to fool a stranger. But the slight rightward hook in my last name was wrong. Mine flowed from the wrist; this one had been copied slowly.
Beneath it sat a notary seal and a reference to a power of attorney granted to Melissa.
That was when the memory surfaced.
Three years earlier, after a car crash broke my wrist, my attorney drafted a narrow power of attorney so Melissa could settle the insurance claim and renew my lease. It expired after thirty days, and I filed a written revocation afterward.
Dead document. Dead authority.
I clicked into the loan disbursement record.
The funds had passed through an old joint checking account Melissa still shared with her husband, Grant.
I leaned back and looked toward the dark living room. Grant’s restaurant had opened eighteen months earlier in the arts district, all marble and expensive lighting. Melissa had called it his “one big shot.” I had quietly wondered how they were paying for it.
Now I knew.
My phone was already in my hand when professional habit stopped me. I called my attorney, Daniel Cho, instead.
He listened without interrupting. When I finished, he said, “Do you still have the trust documents?”
I looked toward my home office.
Ten months earlier, before leaving to care for Mom, Daniel had helped me transfer the townhouse into the Vance Family Revocable Trust, with me as sole trustee. It was boring estate planning, the kind of paperwork families joke about until they need it.
I opened the steel safe and carried the accordion file to the dining table.
The recorded transfer date was two months before the fraudulent loan.
I called Melissa.
She answered on the second ring. “You’re home? Why didn’t you tell me? How’s Mom?”
“Eight o’clock,” I said.
A pause. “What?”
“You and Grant. My house. Eight.”
“Claire, is something wrong?”
I looked at the foreclosure notice lying beside the trust certificate.
“You already know what’s wrong.”
She did not answer.
Part 2: My Sister Arrives With Excuses, Tears, and an Expired Power of Attorney
At 7:58, I heard a key turn in the front door.
That bothered me more than I expected. Melissa still had the spare key I gave her years ago, back when we watered each other’s plants and showed up without calling. Grant walked in behind her wearing a charcoal jacket and the silver watch I remembered seeing in the restaurant’s opening-night photographs.
They stopped at the dining room entrance.
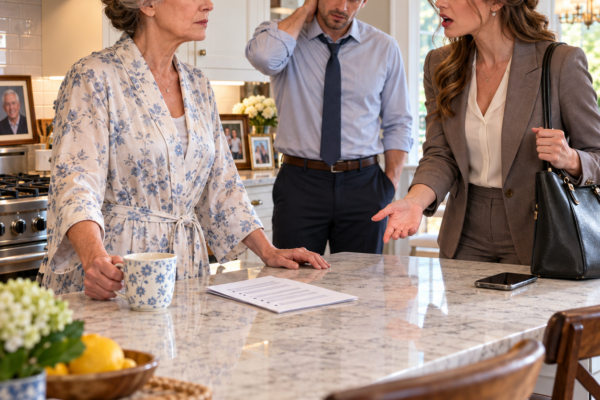
I had arranged the foreclosure notice, loan file, expired power of attorney, revocation letter, and trust documents in neat rows.
Melissa’s eyes moved from one page to the next. Grant looked at me.
“You’ve been busy,” he said.
“Sit down.”
Melissa sat first. Grant waited a beat, then took the chair beside her.
He began with the restaurant, not the signature or the mortgage.
“We hit a cash-flow wall last winter,” he said. “It wasn’t because the business was failing. We had construction overruns, then the liquor license delay, then payroll—”
“You borrowed eight hundred thousand dollars against my house.”
“We leveraged an asset temporarily.”
I slid the signature page toward him. “Whose handwriting is that?”
His jaw shifted.
Melissa whispered, “Claire.”
I turned to her. “Whose handwriting?”
Tears gathered in her eyes. “Grant said the power of attorney was still usable.”
Grant looked sharply at her. “That is not what I said.”
“You said the bank only cared that it existed.”
“I said the paperwork had already been accepted before.”
I watched them begin to separate from each other in real time, each sentence creating a few more inches of distance.
“You notarized this through Evan Pike,” I said. Evan was Grant’s college friend, a notary who had attended two Christmas dinners at Melissa’s house. “He notarized a document I never signed, using authority that expired three years ago.”
Grant folded his arms. “Evan relied on the documentation he was given.”
“That sentence won’t help Evan.”
Melissa pressed both hands to her face, then lowered them. “We were going to pay it back.”
“With what?”
“The restaurant was supposed to turn.”
“Supposed to?”
Grant lost some of his polish. “Businesses need bridge money. You had savings and a paid-off home. We were trying to save something we built.”
I looked at him. “You were trying to save it with something I built.”
Melissa flinched.
For a moment, only the refrigerator motor broke the quiet.
Then Melissa said, “If you pay the arrears, it buys us time.”
That was the first completely honest word anyone had said.
“Us.”
She closed her eyes.
Grant leaned forward. “Claire, litigation will eat you alive. Even if you’re technically right, banks drag these things out. Attorneys, hearings, title fights. You could spend six figures proving a point.”
“You researched that?”
“I’m being realistic.”
“No. You researched how trapped I would feel.”
His face hardened. I took the trust certificate from the bottom of the stack and placed it on top.
“Tell me what this is.”
He glanced down. “Some estate document.”
“It transferred ownership of this townhouse to the Vance Family Revocable Trust ten months ago.”
Melissa frowned. Grant went very still.
“The mortgage was recorded eight months ago,” I continued. “You checked the tax database. You didn’t perform a current title search.”
Grant picked up the certificate.
“You mortgaged property I did not personally own. And a personal power of attorney—expired or not—doesn’t authorize you to encumber trust property.”
His eyes moved across the page faster now.
Melissa looked from him to me. “What does that mean?”
I reached for my phone.
“It means the house was never yours to gamble with.”
Part 3: The Bank Call Turns Their Clever Scheme Into Evidence
Grant stood as soon as he saw the number I was dialing.
“Don’t do this tonight.”
I put the phone on speaker.
“Claire,” Melissa said, “please.”
I raised one finger, not to silence her, but because a recorded menu was asking me to select an option. Fraud. Mortgage. Urgent foreclosure matter.
A senior investigator named Aaron Bell joined the call. His tone was careful and flat, the way professionals sound when every word may later be replayed.
I gave him the loan number, parcel number, recording dates, and the reference number on the expired power of attorney. Then I told him the property had been transferred into a trust before the loan originated.
Keyboard clicks came through the speaker.
Grant moved toward the kitchen, then stopped near the counter. Melissa sat with her hands knotted in her lap.
Mr. Bell asked, “Ms. Vance, are you stating that you did not execute the deed of trust?”
“I did not.”
“And did you authorize Melissa Harper to execute it on your behalf?”
“No.”
Melissa made a small sound.
He asked for the county recording information on the trust transfer. I read it aloud.
More typing.
Then: “I’m placing a temporary hold on foreclosure activity while we verify title and execution. Please remain on the line.”
Grant mouthed, Hang up.
I looked at him and did nothing.
When Mr. Bell returned, his voice had changed. Not dramatically. Just enough.
“The title record confirms the trust acquired the property before our lien was recorded. I’m also seeing discrepancies in the underwriting file regarding verification of ownership and power-of-attorney authority.”
Grant sat down.
Mr. Bell continued. “The bank will suspend the foreclosure immediately. Based on what you’ve reported, this matter must be escalated to our fraud and compliance teams.”
Melissa leaned toward the phone. “Can’t we just repay it?”
“May I ask who is speaking?” Mr. Bell said.
No one answered.
“My sister,” I said. “Melissa Harper.”
Another pause.
“Ms. Harper, I can’t discuss liability with you. I can tell Ms. Vance that accounts connected to the loan proceeds may be restricted pending review. Depending on the movement of funds and the documentation involved, the bank may also be required to file regulatory reports and refer the matter to law enforcement.”
Grant rubbed both hands over his face.
Melissa stared at me as if I had personally invited federal agents into the dining room.
When the call ended, she whispered, “You can stop this.”
“No,” I said. “I could have hidden it. That’s different.”
“We’re your family.”
I looked at the spare key on the table between us. At some point, she had taken it from her purse without me noticing.
“Family doesn’t need a forged signature.”
Her mouth trembled. “You were gone. Mom needed you. The restaurant was collapsing. Grant had put everything into it, and I was terrified we’d lose the house, the business, all of it. You’ve always been the one who lands on her feet.”
There it was: the private arithmetic beneath the betrayal. My stability had become something they felt entitled to use.
“You decided I could survive what you couldn’t.”
She looked down.
Grant said, “We made a bad decision.”
I met his eyes. “A bad decision is opening a second restaurant before the first one makes money. This took paperwork, a notary, a copied signature, a loan application, and eight hundred thousand dollars.”
He had no answer.
I slid the spare key toward myself.
“Leave.”
Part 4: The House Survives, but My Family Does Not Return
The foreclosure notice came off my door the next morning.
I peeled it slowly, careful not to tear it, and placed it in a folder Daniel labeled EVIDENCE. Over the next two weeks, I gave copies of the trust documents, revocation letter, loan file, and bank records to investigators. Pinnacle Union sent me written confirmation that the foreclosure had been canceled and that its lien claim against the trust property would not be enforced.
The bank had problems of its own: an expired power of attorney had been accepted, ownership verification had failed, and a ruinous loan had been approved because the paperwork looked close enough.
Melissa called every few days at first.
I answered once.
“Mom keeps asking why we’re not speaking,” she said.
“Then tell her the truth.”
“I can’t tell her this.”
“You could mortgage my house, but you can’t tell Mom why?”
“That’s not fair.”
I looked around my kitchen—the same kitchen she had stood in years earlier baking Dad’s birthday cake after he got too sick to go out. Memory is inconvenient that way. It refuses to turn people into villains just because they hurt you.
“I’m not asking you to disappear,” I said. “I’m asking you to stop making me responsible for the consequences.”
She was quiet for a long time.
Then she said, “I thought you’d help me.”
“I have helped you.”
“I know.”
“No, Melissa. I don’t think you do.”
That was our last real conversation for months.
Grant’s restaurant closed after creditors moved against the business. Their accounts tied to the loan proceeds were frozen during the investigation, and assets were sold to cover legitimate debts. Evan, the notary, retained counsel. Melissa and Grant did too.
I did not celebrate any of it.
Revenge stories make justice look like champagne and applause. Real consequences are quieter. My sister sounded smaller through Mom’s phone. Grant vanished from family photographs. Thanksgiving became a scheduling problem.
The criminal case took time. Investigators traced the loan proceeds through the joint account and into restaurant expenses, vendor payments, old debts, and personal charges. Melissa eventually admitted that she had signed my name after Grant told her the old power of attorney would protect them. Grant admitted he knew I had not approved the loan, though he continued to insist he believed they could repay it before I returned.
That was the part that stayed with me.
Before I returned.
My six-month absence had not been an inconvenience to them. It had been an opportunity.
The trust had saved the townhouse, but not because I had predicted betrayal. I had created it because Daniel told me adults with aging parents and assets should plan for complications. One ordinary, unglamorous decision made ten months before the fraud became the wall they could not get through.
Months later, I replaced the front lock.
The locksmith held up the old cylinder and asked whether I wanted extra copies.
“Two,” I said.
One for me.
One for Daniel’s office safe.
No family spare.
That evening, I sat on the front steps with a cup of coffee while the porch light came on automatically. The brass house numbers were still a little crooked. The adhesive from the foreclosure notice had left a pale rectangle on the paint, visible if you knew where to look.
I decided not to repaint it.
Not yet.
Some marks are useful.
They remind you that a locked door is not cruelty. A boundary is not punishment. And love, however deep its history, does not require you to hand someone the key after they have already used it to enter your life and take what was never theirs.
The End .
All characters and events in this story are fictional, created for storytelling and entertainment purposes. Thank you sincerely for reading. Your feedback and support are invaluable and motivate me to continue sharing more stories with you.