My Parents Gave My Brother $400,000 for His Failed Business—Then Demanded $96,000 From Me to Save Their Hou
My Parents Gave My Brother $400,000 for His Failed Business—Then Demanded $96,000 From Me to Save Their House
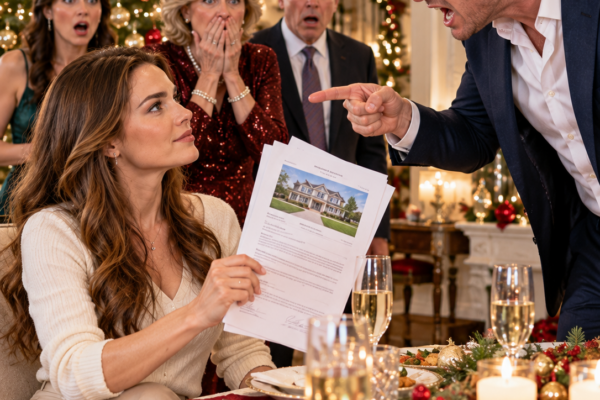
“Your brother’s company is bankrupt, and you’re going to save our house!” My mother slammed a foreclosure notice onto my kitchen table while my father sat silently beside the son they’d handed $400,000. Seven years earlier, those same parents refused to lend me $15,000 to start my business, telling me successful people never needed handouts. Now they wanted $96,000 before 5 PM, or they’d lose everything. I had the money, but the documents I’d uncovered that morning meant they wouldn’t be getting it on their terms.
Part 1
“Your brother’s company failed, and we need you to save the house.” My mother, Celia Ward, delivered that sentence across my kitchen table at 8:17 on a Thursday morning, as casually as if she were asking me to pick up milk. My father, Martin, stared into a mug of coffee he hadn’t touched, while my younger brother, Colin, sat beside him wearing a designer jacket that probably cost more than my first office desk. I looked at the three of them, then at the foreclosure notice Mom pushed across the polished wood, and realized they’d come to my house expecting a rescue, not a conversation.
The notice demanded $96,000 to satisfy the accelerated home-equity debt and associated charges before the lender proceeded toward foreclosure. My parents were three months behind on payments, their savings were gone, and the house they’d owned for twenty-seven years was now collateral for my brother’s failed business. Mom reached across the table and squeezed my wrist, wearing the same pleading expression she used whenever she needed me to forget something hurtful. “Evan, you’re the only person in this family who can fix this,” she whispered, as though that made the situation my responsibility.
Seven years earlier, I’d sat at their dining table with a business plan, asking for a $15,000 loan to establish my accounting practice in Dallas. Dad had barely glanced at the projections before declaring that adulthood meant learning to stand on your own. Mom agreed, explaining that I’d appreciate success more if nobody gave me anything. I remembered driving away in my ten-year-old Honda with the air conditioner rattling and my throat tight, wondering why asking for help had suddenly made me such a disappointment.
I built my practice anyway, renting a cramped upstairs room above a dental office where the hallway always smelled faintly of disinfectant. I spent weekends preparing returns for small businesses, studied financial fraud cases after midnight, and ate enough canned soup to make the grocery-store aisle unbearable. Some months, paying the office rent meant postponing my own car repairs, and once I slept beneath my desk because driving home seemed like wasted time. Seven years later, my forensic-accounting firm employed nine people, served clients across Texas, and generated the kind of steady income I’d once considered impossible.
Colin’s experience with our parents had been completely different. Three years earlier, he’d announced plans to launch a revolutionary logistics platform in Austin, promising that his software would transform commercial freight transportation. He had no software development experience, no paying customers, and no finished product, but Dad called him a visionary and Mom told everyone he was building the next great American technology company. They invested $200,000 from retirement savings, another $120,000 from brokerage accounts, and eventually $80,000 borrowed against their home.
I’d warned them after seeing Colin’s first investor presentation, which consisted mostly of colorful graphics and impressive predictions unsupported by actual contracts. Dad accused me of being jealous, and Colin laughed that an accountant wouldn’t understand disruptive technology. Soon my brother had twelve employees, an expensive downtown office, and a Porsche leased through the company, even though his product still wasn’t operational. Every few months, he announced that investors were practically fighting to finance his next stage, and my parents proudly repeated whatever numbers he gave them.
Now those numbers had apparently disappeared. I asked Colin how much cash remained, and he mumbled, “Nothing,” without meeting my eyes. Dad finally looked up and admitted they’d made a mistake, but insisted losing the house wouldn’t teach anyone anything. I asked whether transferring the consequences of their mistake to me was supposed to teach me something instead.
Dad’s expression hardened immediately. “Watch your mouth, Evan,” he snapped, tapping the foreclosure notice with one finger. “You have a successful company and a beautiful four-bedroom home, so don’t pretend ninety-six thousand dollars is going to ruin you.” Mom nodded, adding that family members were supposed to support one another during emergencies. I looked at Colin, waiting for him to acknowledge his role, but he was studying the gold watch on his wrist.
I could have written the check, and that was exactly what frightened me. My parents knew I’d recently expanded my business, and they clearly believed financial success had transformed me into their personal emergency fund. What they didn’t know was that Mom had sent me a photograph of the foreclosure notice at six that morning, and I’d spent the next two hours examining county property records. Something in those records didn’t match the simple story they were telling me.
I folded the notice, placed it beside my coffee, and asked one question that made my father’s face change. “Before we discuss money, Dad, why does the county record show you were negotiating another loan against the house three weeks ago?” Colin stopped looking at his watch, and Mom’s hand slowly withdrew from the table.
Part 2
Dad leaned back, folding his arms with the irritated confidence he used whenever he wanted an uncomfortable subject to disappear. “I talked to a lender about refinancing, Evan, because your brother was trying to salvage his company,” he said. “There was nothing wrong with exploring our options.” I opened my laptop and turned the screen toward him, displaying a recorded power of attorney granting Colin authority to negotiate additional financing secured by their property. It had been signed three weeks earlier, long after Colin had privately admitted his company was running out of money.
Mom claimed it was merely a precaution, but the dates told a different story. The document gave Colin considerable authority to negotiate on their behalf, and its accompanying correspondence referenced a proposed $65,000 emergency credit facility. I asked whether the financing had closed, and Dad admitted the lender had rejected the request after reviewing the existing debt and the company’s financial statements. Colin finally spoke, insisting he’d been only days away from securing a major transportation contract when everything collapsed.
“Show me the contract,” I said, sliding my laptop toward him. Colin looked offended and claimed the negotiations were confidential, although his company had already stopped operating. I reminded him that confidentiality wouldn’t prevent him from showing his own family evidence of a genuine business opportunity. He muttered something about lawyers, and Dad immediately demanded that we stop discussing the failed company and concentrate on the house.
That familiar maneuver nearly made me laugh. Every time Colin faced consequences, our parents redirected the conversation toward someone else’s responsibility to protect him. At twenty-nine, he’d never held a conventional salaried job for more than six months, yet he’d somehow convinced them he possessed extraordinary business instincts. I had watched this performance for years, but now the ticket price was their home.
Mom pushed the foreclosure warning closer and pointed at the deadline. “We don’t have time to conduct an investigation, Evan,” she said, her voice becoming sharp. “Either you’re helping us or you’re standing by while your elderly parents lose everything.” I asked her whether she’d considered selling the property before the situation became desperate, and she looked at me as though I’d suggested abandoning a family member. “That house is your father’s legacy,” she answered. “We shouldn’t have to sacrifice it when our successful son has more than enough money.”
I opened my financial notebook and wrote down the numbers they had confirmed. Their original $80,000 home-equity borrowing had grown through accrued charges, missed payments, and collection expenses into the $96,000 payoff demand sitting before us. Their retirement savings and investment accounts had already been depleted, and Colin’s remaining personal guarantees were separate obligations that wouldn’t disappear if I saved the property. The business had produced no reliable revenue, and no one at the table could identify a realistic source of repayment.
“How much do you owe personally, Colin?” I asked. He claimed he wasn’t certain because several creditors were still calculating balances, which was an astonishing answer from the person who’d signed those agreements. When I suggested he sell the Porsche and terminate his expensive apartment lease, he accused me of enjoying his humiliation. “You always wanted me to fail,” he snapped, pushing his chair away. “You can’t stand that Mom and Dad believed in me.”
I remembered the night I’d received my first significant corporate investigation contract, after spending eighteen months struggling to keep my office open. I’d called our parents because I wanted them to hear the good news, and Dad had interrupted me to discuss Colin’s acceptance into an entrepreneurship program. Mom had promised we’d celebrate my accomplishment another time, but that celebration never happened. Sitting across from them now, I realized they remembered my successful business only when it became useful to them.
I asked all three to leave while I reviewed the documents and spoke with an attorney. Mom protested that they couldn’t afford delays, but I promised to give them a definite answer before the lender’s deadline. Dad stood abruptly, warning me that family loyalty was more important than paperwork, and Colin followed him toward the door without offering a single apology. Mom lingered long enough to whisper, “You know we’d do the same for you,” although the evidence of my entire adult life suggested otherwise.
After they left, I called the loan servicer with my parents’ written authorization and confirmed the amount required to resolve the delinquent home-equity obligation. Then I contacted a real-estate attorney named Lauren Keene, who’d handled several property transactions for my business clients. As I emailed her the documents, another message arrived from Colin, clearly intended to frighten me into surrendering. “If you don’t pay, everyone will know you had the money to save our parents and refused.”
I almost deleted it, but something attached to his message caught my attention. It was an investor summary showing that he’d recently listed our parents’ house as a potential source of collateral for another business venture. The document wasn’t proof of a completed loan, but it revealed something I hadn’t understood until then. Even after losing $400,000, Colin was still making plans that depended on our parents’ home, and I knew a simple bailout would leave them exposed to the same disaster again.
Part 3
Lauren returned my call shortly after eleven and asked me to describe precisely what my parents wanted. I explained the foreclosure deadline, Colin’s failed company, and the request for $96,000, along with the newly discovered borrowing authorization. She listened without interrupting, then asked whether I intended to give my parents the money as a gift or recover it later. When I admitted I hadn’t decided, she said something that immediately clarified the problem: “Evan, if you pay their debt without changing anything else, what prevents them from borrowing against the house again?”
That question stayed with me as I drove to Lauren’s office near downtown Dallas. Her conference room overlooked a busy intersection, and I could hear the low rumble of construction equipment outside while she examined the documents I’d brought. She confirmed that my parents remained the owners and had the right to decide what happened to their property, regardless of how foolishly they’d handled their money. She also explained that a properly structured purchase, combined with protected lifetime occupancy rights, could preserve their housing while preventing another round of reckless borrowing.
We discussed an arrangement that would place legal ownership with a holding company I controlled while giving my parents enforceable rights to remain in the house for their lifetimes. The transaction would need a title examination, lender payoff verification, signed conveyance documents, and an independent explanation of what my parents were surrendering. Lauren insisted that the house’s value and the cost of lifetime occupancy be professionally documented so nobody could reasonably claim I’d hidden the consequences. I agreed immediately because I wanted legal protection, not an opportunity to exploit their desperation.
The more we discussed the arrangement, the more I understood how different my response would be from Colin’s approach to money. I wasn’t interested in impressive promises, dramatic projections, or taking unnecessary risks with other people’s financial security. My accounting firm maintained operating reserves, paid its employees on time, and never treated future revenue as though it already existed. The $96,000 wouldn’t bankrupt me, but it represented capital I’d earned through years of disciplined work, and I refused to throw it into another financial disaster without safeguards.
Lauren contacted the loan servicer and received written confirmation of the amount needed to satisfy the accelerated home-equity obligation. The lender agreed to accept funds through the title company’s escrow process, provided the documentation and payment arrived before the stated deadline. A preliminary title examination revealed no additional recorded mortgage beyond the existing loan, although Colin’s recent power of attorney made revocation essential. We prepared a conditional purchase agreement and arranged for my parents to receive independent legal advice before deciding whether to proceed.
I returned home shortly after noon and found another message from Mom. She’d attached a photograph of their living room, complete with the faded family portraits and the old grandfather clock Dad had inherited from his uncle. Beneath it, she’d written, “Think about all the memories you’re about to destroy.” I stared at the photograph, remembering how often I’d sat in that same room listening to my parents praise Colin while treating my accomplishments like minor inconveniences.
I replied that I had a proposal they needed to examine with their own attorney, and that it would protect their ability to remain in the house. Mom called immediately, her voice brightening when she heard I’d found a possible solution. But when I explained that I wouldn’t provide an unsecured loan or gift, her enthusiasm vanished. “You’re making your father jump through hoops just to save his own home?” she demanded. “What kind of son uses his parents’ misfortune to negotiate?”
“The kind who understands what happens when people borrow money they can’t repay,” I answered. I told her the proposal would preserve their housing, eliminate the immediate debt, and prevent Colin from using the property as collateral again. She insisted that Colin deserved another opportunity and that I couldn’t possibly understand how much pressure he was under. I reminded her that she hadn’t worried about my pressure when I was working weekends to keep my first business alive.
An hour later, Dad called and asked me to meet them at the title company’s office. His voice was quieter than it had been that morning, but he still wanted reassurance that I wasn’t planning to throw him and Mom out. I explained the lifetime occupancy protections again and told him an independent attorney would review everything with them before any signatures. He paused, then admitted that their regular lawyer had already warned them their choices were extremely limited.
I was gathering my documents when Lauren forwarded an additional email she’d obtained from the family’s attorney with my father’s permission. It included a draft proposal Colin had circulated only days before the foreclosure warning reached me. Under that arrangement, my parents would have remained responsible for the debt while Colin obtained future rights to manage and potentially acquire the property through his company. My name appeared nowhere in the proposal, despite the expectation that I’d provide the money necessary to save it.
I called Dad again and asked whether he’d known about Colin’s plan. He remained silent long enough for me to hear the television playing in the background, then admitted he’d discussed the possibility with my brother. “We thought you might help temporarily,” he said, “and once Colin recovered, everything would work out.” I looked at the agreement he’d almost signed and realized they hadn’t merely expected me to rescue the house. They’d been preparing to let Colin control it afterward.
Part 4
By two that afternoon, we were sitting in a conference room at the title company’s office, surrounded by documents that would determine whether my parents kept their home. Dad sat beside an independent attorney Lauren had recommended, while Mom studied the purchase agreement with an expression of open suspicion. Colin had insisted on attending, although he wasn’t a party to the transaction and had no legal authority over the house. He spent the first fifteen minutes complaining that I was turning a family emergency into a business negotiation.
I placed the proposed agreement in front of my parents and explained it without using legal jargon. I would provide the funds necessary to eliminate the home-equity debt through escrow, and ownership would transfer to my holding company under terms reflecting the property’s value and their lifetime occupancy rights. They could remain in the house without rent, and my company would handle property taxes and major structural repairs while they remained responsible for ordinary utilities and personal expenses. Their occupancy protections would be documented, but they couldn’t mortgage, sell, or pledge the house to anyone.
Dad read the document slowly, then looked at me with an expression I couldn’t quite identify. “You want me to sign away the house I worked thirty years to buy?” he asked. I reminded him that he’d already placed the house at risk to finance Colin’s business, without asking whether I approved. “I’m offering to make sure you and Mom never have to worry about losing your home again,” I said. “But I’m not giving you ninety-six thousand dollars so Colin can find another way to spend it.”
Colin pushed back his chair and demanded to know what would happen to his personal guarantees. He explained that several creditors were threatening legal action and that selling the Porsche wouldn’t cover everything he owed. I suggested he speak with a bankruptcy attorney, end the unnecessary expenses, and begin looking for salaried work. “You think I should become some ordinary employee after building a technology company?” he demanded, and I answered, “You didn’t build a functioning company, Colin. You spent four hundred thousand dollars preparing to build one.”
Mom began crying, accusing me of humiliating my brother when he was already suffering. She reminded me that I’d never been interested in technology and therefore couldn’t appreciate the difficulty of launching a revolutionary business. I asked whether she appreciated how difficult it had been to launch my accounting firm with no family support. She looked away, and I realized that even with foreclosure approaching, she still couldn’t bring herself to admit how differently she’d treated her sons.
The independent attorney asked everyone except my parents to leave while he reviewed the agreement and its consequences with them privately. I waited in the hallway beside a vending machine, listening to Colin pace while he complained that I’d manipulated the situation. He demanded that I give him enough money to settle his most aggressive creditors, promising he’d repay me once his next venture succeeded. I told him there would be no investment, no loan, and no co-signature, and he walked away muttering that I’d always been a selfish brother.
Twenty-five minutes later, the conference room door opened, and Dad asked me to come inside. His face looked older than it had that morning, and the anger in his eyes had faded into exhaustion. “Your attorney says this arrangement can protect our right to stay, and ours has explained what ownership we’d be giving up,” he said. Then he looked toward Mom and added quietly, “We already gambled the house on Colin, Celia. We don’t get to gamble it again.”
Mom pleaded with him to reconsider, insisting we could find another solution if everyone stopped rushing. Dad pointed toward the foreclosure notice and reminded her they had exhausted every conventional option before coming to me. He took the pen offered by the closing agent, reviewed the signature pages once more, and signed the necessary documents. Mom eventually signed as well, although she refused to look at me afterward.
The closing agent completed the escrow instructions, and I authorized the transfer from my company’s designated account. Shortly after four, the title company received confirmation that the lender had accepted the required funds and the documents necessary to discharge the debt. The executed conveyance would be submitted for recording, and my parents’ protected occupancy arrangement would remain part of the transaction. I felt no desire to celebrate as I watched years of my family’s poor decisions become my financial responsibility one final time.
Colin left before the final confirmation arrived, slamming the glass office door hard enough to make the receptionist flinch. Mom followed him without saying goodbye, leaving Dad standing beside the conference table with his coat folded over one arm. “I suppose you think you’ve won,” he said quietly. I looked at the signed documents, then at the man who’d taught me that asking for help was weakness while funding every reckless idea his favorite son invented. “No, Dad,” I answered. “I think I’ve finally stopped losing.”
Part 5
Six months after the closing, my parents were still living in the same house they’d almost lost. The oak tree in the front yard was still dropping leaves onto the driveway, and the porch light Dad had installed twenty years earlier still illuminated the brick walkway each evening. Their daily lives had changed surprisingly little, except that they could no longer borrow against the property or promise it to Colin. My holding company paid the taxes, maintained the structure, and honored every protection they’d received in the agreement.
My relationship with them, however, had changed completely. Mom called repeatedly during the first month, sometimes thanking me for saving their home and sometimes accusing me of stealing their inheritance. She wanted me to bring the family together for dinner and pretend the entire incident had been a misunderstanding. I declined, explaining that paying off their debt didn’t erase the years of favoritism or the morning they’d demanded my money without acknowledging my sacrifices.
Colin’s situation deteriorated before it improved. He eventually sold the Porsche, moved out of his expensive apartment, and began negotiating settlements with several creditors after consulting an attorney. According to a cousin, he found a sales position with a transportation equipment supplier, which was the first steady salaried job he’d held in years. I hoped he’d learn something from the experience, but I had no interest in financing his education through another expensive mistake.
My accounting firm continued growing, and I hired two additional forensic analysts to handle an expanding caseload. For the first time since starting the business, I took a full week away from work without bringing my laptop, spending several days hiking in Colorado with friends. Standing beside a mountain lake one morning, I realized how rarely I’d allowed myself to enjoy the success I’d earned. I’d spent years trying to prove my worth to people who had already decided which son deserved admiration.
Dad contacted me again in November, asking whether I’d reconsider placing the house in a family trust that would eventually benefit both Colin and me. He explained that Colin had made progress and deserved another chance to build some financial security. I reminded him that the house was protected precisely because nobody could use it to finance my brother’s ambitions anymore. Dad grew irritated and suggested I was punishing Colin for mistakes that had already cost him everything.
“You’re still trying to protect him from the consequences,” I replied. “And you’re still treating what I earned as something he has a right to receive.” Dad remained silent for several seconds before telling me he didn’t recognize the man I’d become. I told him that was probably because he’d never spent much time trying to understand me in the first place.
At Christmas, Mom sent a long message describing how lonely the holidays felt without everyone together. She included photographs of the dining table where we’d celebrated birthdays, graduations, and countless family dinners over the years. I remembered those gatherings differently from her, particularly the way my accomplishments had been brushed aside whenever Colin had something to announce. I replied that I was glad they still had their home, but I wouldn’t be attending Christmas dinner or reopening our relationship.
A few days later, Dad left a voicemail that sounded more sincere than anything he’d said during the previous six months. He admitted he’d made terrible financial decisions and that he’d treated Colin’s ambitions as more important than my hard work. He said he wished he’d supported me when I was twenty-six and understood that my success had come from sacrifices he’d never properly acknowledged. I listened twice, recognizing that he’d finally said the words I’d once desperately wanted to hear.
But those words arrived after I no longer needed them. I didn’t return the call, and I didn’t feel guilty about it, because recognizing someone’s regret didn’t obligate me to rebuild a relationship that had repeatedly hurt me. My parents had a secure place to live, Colin had the opportunity to support himself, and I had fulfilled every promise I’d made during the closing. I no longer needed to sacrifice my peace simply to prove I was a good son.
On the anniversary of the foreclosure crisis, I found the original business plan I’d shown Dad seven years earlier. It was tucked inside an old filing cabinet, its pages yellowed and covered with handwritten calculations for office rent, software subscriptions, and marketing costs. On the last page, I’d written a sentence that made me smile: “If nobody believes in this business, I’ll build it anyway.” I framed that page and hung it in my office, where I could see it every morning.
Later that evening, I stood on the back patio of my own home, watching the last sunlight disappear behind the neighboring rooftops. My phone vibrated with another message from Mom, but I left it unanswered and returned to the quiet dinner I’d prepared for myself. For seven years, my family had insisted that independence was the greatest lesson I could learn, while shielding Colin from that same lesson at every opportunity. In the end, the child they’d refused to help became the only one capable of saving their house, but saving their house was where my responsibility ended.
I hadn’t rescued my family to earn their love, and I hadn’t taken control of the property to make them suffer. I’d simply stopped allowing their mistakes to become my emergencies. The roof over their heads was secure, my business belonged to me, and my future was finally free of the endless obligation to prove that I deserved the respect they’d always given my brother. Their love had arrived with conditions, excuses, and demands, but the life I’d built no longer needed their approval.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓